
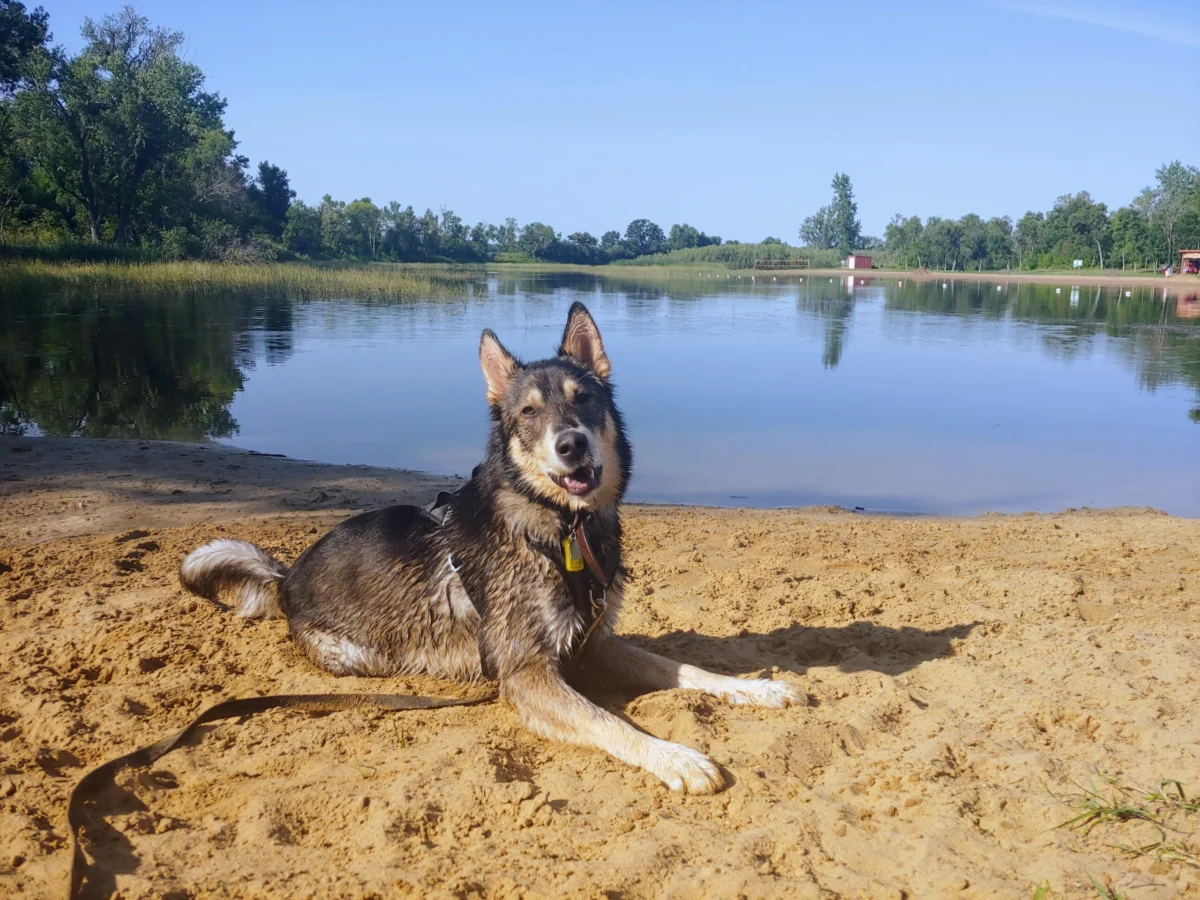
Sam and Riley, a 36-year-old married couple residing in Winnipeg, Manitoba, represent a demographic of Canadian professionals navigating the complex intersection of mid-career pivots, the rising costs of homeownership, and the time-sensitive nature of family planning. As they enter their mid-30s, the couple faces a series of concurrent financial and personal milestones that require a meticulous strategic approach to ensure long-term stability. Living with their rescue dog, Bisky, and two aging cats, the household is currently balancing a recent home purchase with Sam’s intended transition into a specialized trade and Riley’s potential return to graduate school, all while preparing for the financial implications of starting a family through potential medical intervention.

Regional Economic Context and Household Overview
The couple’s situation is situated within the specific economic landscape of Winnipeg, where the cost of living remains relatively lower than in major Canadian hubs like Toronto or Vancouver, yet is subject to the same inflationary pressures and interest rate hikes seen nationwide. Sam, currently working as a plasterer, is seeking a more sustainable and lucrative career path as a sprinkler fitter, a move that would eventually provide a unionized pension and higher earning potential but requires an initial period of lower-income apprenticeship. Riley, a social worker at a local college, manages a chronic health condition—systemic lupus—which has necessitated leaves of absence and shaped their approach to workplace benefits and disability insurance.
In June 2022, the couple purchased their first home for $282,000, a move that significantly depleted their liquid savings. With a mortgage balance of approximately $257,160 and a fixed interest rate of 5.19%, the household must now reconcile their debt obligations with their desire to increase their net worth and prepare for retirement, ideally between the ages of 55 and 60.

Chronology of Financial Transitions (2015–2023)
The couple’s current financial standing is the result of a decade of professional and personal shifts. Between 2015 and 2019, Riley completed the majority of a Master of Social Work (MSW) degree but was forced to withdraw due to the onset of systemic lupus. During this same period, Sam operated as a chef and restaurant owner, a career path he abandoned in 2019 in favor of the trades, citing the industry’s volatility and lack of long-term security.
The year 2021 marked a turning point with their marriage and a concerted effort to eliminate consumer debt. By 2022, Sam’s transition to plastering and Riley’s increase to full-time hours allowed them to secure a mortgage. However, the subsequent "totaling" of their vehicle in late 2022 served as a catalyst for a more frugal mindset. Rather than taking on a new car loan, they utilized insurance proceeds to pay off an existing loan and purchase a used vehicle outright, a decision that improved their monthly cash flow by several hundred dollars.

Supporting Data: Income, Debt, and Asset Breakdown
The household’s financial health is characterized by a stable but moderate income and a manageable debt-to-income ratio, though their liquid assets remain low following their home purchase.
Annual Income and Cash Flow
The combined gross income for the household is approximately $131,690, resulting in a total annual net income of $88,870 after taxes, pension contributions, and insurance deductions.

- Riley’s Net Annual Pay: $44,720 (Social Work)
- Sam’s Net Annual Pay: $37,150 (Plastering)
- Variable Income: Includes Sam’s side jobs ($2,500), annual tax returns (~$4,500), and small bonuses.
Debt Profile
The couple carries approximately $19,804 in non-mortgage debt, categorized by varying interest rates:
- Energy Loan (Central Air): $3,828 at 7.70% interest.
- Federal Student Loan: $7,282 at 0% interest.
- Provincial Student Loan: $1,484 at 0% interest.
- RRSP Home Buyers’ Plan Loan: $7,210 (must be repaid to retirement accounts over 15 years).
Asset Portfolio
Total household assets are valued at $45,330, with a significant portion tied up in Riley’s employer pension plan ($25,000). Their liquid emergency fund stands at $9,634, which covers less than two months of their current monthly spending of $6,156.

Strategic Analysis of Education and Career Pivots
A primary dilemma for the household is the timing of Riley’s MSW completion. In the Canadian academic system, graduate credits often have a "stale-date," typically expiring after seven to ten years. If Riley does not complete the degree by the 2023–2024 academic year, they risk losing the investment previously made in their education.
From a financial perspective, the MSW represents a calculated risk. While Riley’s employer offers partial tuition reimbursement, the degree’s immediate impact on salary is not explicitly guaranteed in their current role. However, an MSW often serves as a prerequisite for advanced clinical roles or private practice, which could significantly increase Riley’s lifetime earning ceiling.

Simultaneously, Sam’s transition to sprinkler fitting is viewed as a long-term play for stability. As a Red Seal trade in Canada, sprinkler fitting offers a clear wage progression. Apprentices typically start at a percentage of a journeyperson’s wage, reaching full pay (often $40-$50 per hour in unionized environments) after four to five years. The trade also provides a robust pension plan, which is essential given the couple’s current lack of private retirement savings.
Family Planning and IVF Implications
The most pressing emotional and financial variable is the couple’s desire to have a child. At age 36, they are acutely aware of the biological window for conception. They have budgeted for In Vitro Fertilization (IVF) should natural conception not occur by late 2023.

In Manitoba, the financial burden of IVF is mitigated by the Provincial Fertility Tax Credit, which allows residents to claim 40% of treatment costs up to a maximum credit of $8,000 annually. Despite this, the upfront costs are estimated at $14,000 plus medication. While Sam’s health insurance covers 80% of medication costs, the household still faces a significant out-of-pocket expense.
Furthermore, Canadian Employment Insurance (EI) provides parental benefits at 55% of earnings up to a maximum of $650 per week. Riley’s employer offers a "top-up" to 90% for 17 weeks, but this benefit is tied to their current salary. If Riley is in school or on reduced hours when the baby arrives, the total value of these benefits could decrease, creating a temporary but sharp reduction in household income.

Broader Implications and Financial Recommendations
The challenges faced by Sam and Riley reflect broader trends in the Canadian economy, where middle-class households must balance the "triple threat" of high interest rates, education costs, and the expense of modern family building. Financial analysts suggest several key interventions for households in this position.
Debt Prioritization and Cash Flow
The most immediate recommendation for the couple is the elimination of the 7.70% energy loan. While the student loans are at 0% interest—effectively making them "cheap" debt in an inflationary environment—the energy loan represents a significant drag on their wealth-building capacity. By redirecting discretionary spending for approximately three months, the couple could retire this debt and free up monthly cash flow.

Emergency Fund Optimization
With a monthly spend of $6,156, the current emergency fund of $9,634 is insufficient for a household with a member managing a chronic illness. Financial best practices for a dual-income household with health variables suggest a minimum of six months of expenses ($36,936). Building this cushion is critical before Sam enters an apprenticeship or Riley begins a parental leave.
Lifestyle Adjustments
The household’s current discretionary spending on items such as three separate Community Supported Agriculture (CSA) subscriptions, dog daycare, and "spending money" totaling over $1,000 monthly provides a significant buffer for reduction. Analysts point out that "lifestyle creep" often occurs after a home purchase, and a temporary period of extreme frugality could fund both the IVF treatments and the MSW tuition without the need for additional high-interest debt.

Conclusion
Sam and Riley are at a crossroads that requires balancing immediate personal desires with long-term financial security. Their story underscores the importance of strategic sequencing. By prioritizing the elimination of high-interest debt and the fortification of an emergency fund, they can create the stability needed to pursue Riley’s degree and Sam’s career change. While the pressure to start a family is high, doing so from a position of increased liquidity will mitigate the stress of Riley’s health challenges and the inherent volatility of career transitions. As they move forward, their ability to maintain a high savings rate through disciplined spending will be the determining factor in whether they reach their goal of a comfortable retirement by age 55.

