
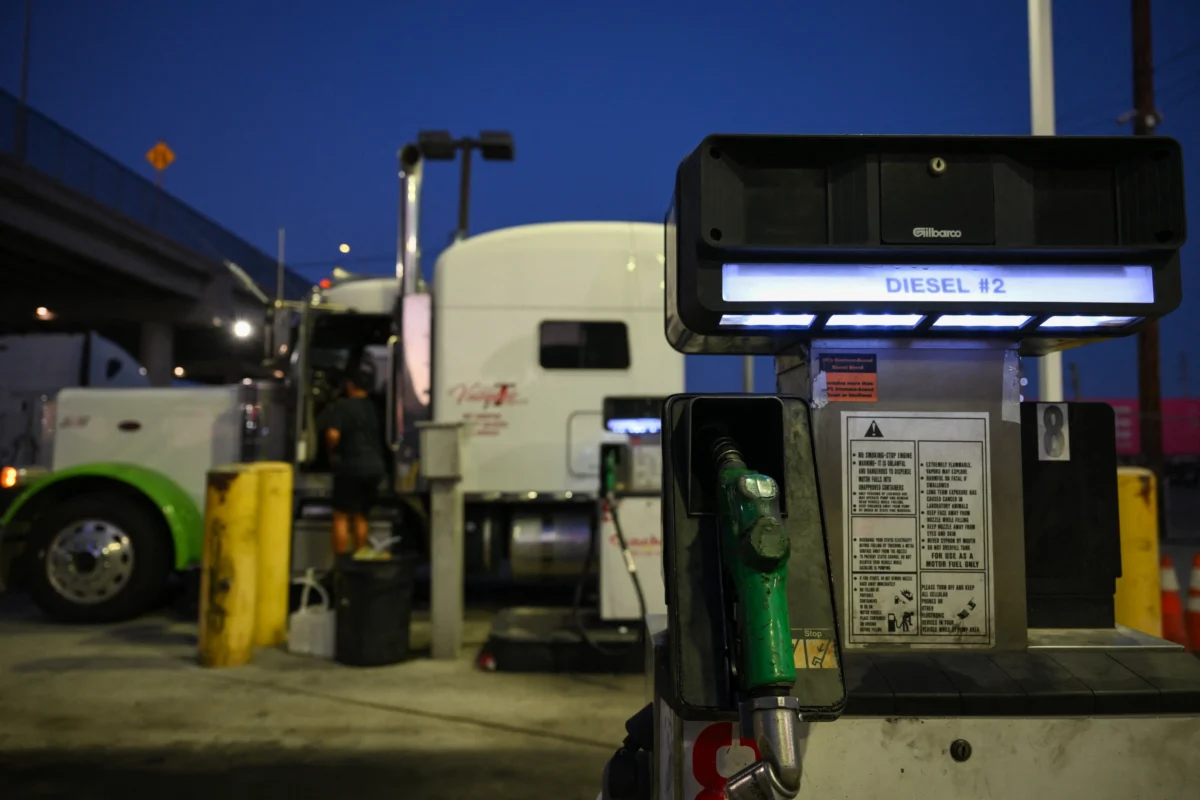
The United States has witnessed an unprecedented surge in diesel fuel prices, with costs exceeding $6 a gallon for the first time ever, as observed at a truck stop in Miami, Florida, on September 11, 2026. This record-breaking price point underscores a deepening global energy crunch, particularly impacting refined petroleum products, and sets the stage for what analysts at Goldman Sachs predict will be a sustained period of elevated diesel prices, potentially extending through 2027. The investment bank attributes this outlook to a complex interplay of persistent refinery constraints clashing with recovering demand and the imperative for companies and governments to replenish severely depleted inventories worldwide.
The Economic Imperative of "Demand Destruction"
According to Nikhil Bhandari, Goldman Sachs’ co-head of Asia-Pacific natural resources research, high product prices are not merely a market anomaly but a necessary mechanism in the current environment. Speaking on CNBC’s “Squawk Box Asia” on Monday, Bhandari articulated a stark reality: "We need to keep product prices high enough to have a certain level of demand destruction continuing next year." This statement highlights the precarious balance the global energy market is attempting to strike, where price acts as a critical governor to prevent surging demand from overwhelming an already strained global refining system.
Goldman Sachs’ projections paint a challenging picture, forecasting that global diesel and jet-fuel crack spreads—the crucial premium that refined products command over crude oil—will average above $40 per barrel in 2027. This figure represents more than double their historical average level of around $20 per barrel, signaling a significant and prolonged squeeze on the supply side of the refined products market. This elevated spread is expected to persist despite the bank’s concurrent forecast for Brent crude, the international oil benchmark, to stabilize at approximately $80 per barrel as recent crude flows through the Strait of Hormuz gradually normalize. The disconnect between stable crude prices and soaring refined product premiums underscores the severity of the bottleneck in refining capacity.
Bhandari further emphasized the scale of the challenge: "If there is any demand rebound next year, we think the global refining system will have to hit the highest utilization rate that we have seen in the last two decades." This suggests that even under optimal operating conditions, the existing refinery infrastructure will be stretched to its absolute limits, leaving little room for error, unplanned outages, or further geopolitical disruptions.
The Resilience of Underlying Demand and Inventory Woes
Despite recent fluctuations and periods of apparent weakness, Baden Moore, a resources and energy research analyst at brokerage CLSA, offers a cautious perspective on demand dynamics. Moore suggests that recent softness in the market does not necessarily signify a permanent loss of demand. In an email to CNBC, he clarified, "Underlying oil-product demand remains largely intact." Instead, buyers have managed to balance the market through a combination of strategic inventory management, drawing down existing reserves, curtailing non-essential consumption, and optimizing refinery operations to maximize output where possible. However, these measures are inherently short-term solutions. Moore estimates that the critical task of replenishing global inventories while simultaneously meeting ongoing demand could take up to two years, further solidifying the outlook for prolonged market tightness.
A Strained Refinery Network Underpins the Crisis
The core of the refined product scarcity lies in a severely constrained global refinery network. Goldman Sachs’ analysis, detailed in its global Refining Super Cycle report published on September 21, highlights that 2026 is expected to mark another year of "negative refining capacity growth." Specifically, refining capacity outside China is projected to contract by approximately 300,000 barrels per day. This contraction is not a new phenomenon; years of underinvestment, the closure of older, less efficient plants, and a broader global push towards decarbonization have led to a structural decline in refining capacity in many developed economies.
Compounding this global trend, significant regional outages further exacerbate the supply crunch. Bhandari pointed out that roughly 2 million barrels per day of Middle Eastern refining capacity remains offline, a substantial volume that would otherwise contribute significantly to global supply. Concurrently, damaged Russian facilities have further restricted the availability of diesel, a critical fuel for both industrial and military operations.
Even active refineries face their own set of challenges. U.S. refineries, which have been running at exceptionally high utilization rates to compensate for falling global capacity, are now facing an inevitable need for deferred maintenance. These crucial maintenance cycles, which ensure the safe and efficient operation of complex refining units, will temporarily reduce refinery runs, further tightening supply in the coming months.

The recovery of Gulf crude exports, while positive for crude oil supply, is not expected to substantially improve refined product availability. Shipments of diesel, gasoline, and jet fuel continue to face restrictions, indicating that the bottleneck is indeed at the processing stage rather than solely at the crude extraction point.
Strategic Releases: A Temporary Reprieve, Not a Solution
The urgency of the situation prompted a significant coordinated response from the Group of Seven (G7) countries. On Friday, the G7 agreed to release 100 million barrels of crude oil and refined products over a four-month period. Crucially, this included a "front-loaded substantial diesel release" within the first 20 days, signaling the immediate priority placed on alleviating the diesel crunch. The announcement had an immediate, albeit temporary, impact on the markets, sending European gasoil futures down by 5.75%.
However, experts are largely pessimistic that these emergency releases will offer a long-term solution to the underlying issues of refined product availability and price moderation. Amin Nasser, the CEO of Saudi Aramco, articulated this sentiment bluntly on Monday, stating that emergency reserves "might buy us a winter," but fundamentally cannot fix the deep-seated, long-term supply problems.
CLSA’s Baden Moore echoed this perspective, emphasizing that "Emergency releases only solve a liquidity problem, not the underlying stock problem." While these releases do provide a temporary injection of supply and buy crucial time, they simultaneously mean that existing inventories are being consumed rather than rebuilt. This, in turn, transforms restocking into a longer-term source of demand, effectively pushing the problem further down the road without addressing its root causes. Bernard Aw, chief economist for Asia-Pacific at Coface, concurred in an emailed statement to CNBC, adding that the impact of such releases is inherently "temporary rather than structural."
Broader Economic and Geopolitical Implications
The sustained high price of diesel carries profound implications for the global economy and geopolitical landscape. As a foundational fuel for global commerce, transportation, and agriculture, elevated diesel costs translate directly into inflationary pressures across various sectors. The trucking industry, which relies almost exclusively on diesel, faces significantly higher operational costs, which are inevitably passed on to consumers in the form of increased prices for goods. Shipping, rail transport, and heavy machinery used in construction and mining are similarly impacted, contributing to a broader inflationary spiral. Farmers, heavily dependent on diesel for tractors and harvesting equipment, will see their input costs rise, potentially leading to higher food prices.
From an economic perspective, this acts as a significant headwind, potentially dampening economic growth as businesses and consumers contend with higher expenses. Central banks, already grappling with inflation, will find their task complicated by energy-driven price increases that are largely outside the scope of monetary policy tools.
Geopolitically, the diesel crisis exacerbates energy security concerns. Nations become more vulnerable to supply disruptions and price volatility, increasing strategic competition for available supplies. The reliance on specific refining hubs or regions with spare capacity becomes a critical factor in international relations. The damaged Russian facilities, for instance, highlight how regional conflicts can have global ripple effects on energy markets, particularly for refined products that are less fungible than crude oil.
Policy implications are also significant. Governments face the difficult task of balancing immediate energy security needs and inflationary pressures with long-term climate goals. The impulse to increase refining capacity or extend the life of existing plants to address the current crisis may clash with commitments to reduce fossil fuel dependence. Finding solutions will require a multi-faceted approach, potentially involving incentives for new, more efficient refining capacity, strategic investments in renewable energy alternatives, and international cooperation to manage supply chains and reserves effectively.
In conclusion, the global diesel crisis is not a transient market fluctuation but a complex, structural challenge driven by years of underinvestment in refining capacity, geopolitical disruptions, and the persistent, underlying demand from a recovering global economy. While emergency releases offer a brief respite, the consensus among experts is that high diesel prices are here to stay for the foreseeable future, necessitating a fundamental re-evaluation of energy infrastructure and policy worldwide.

