
The economic landscape for American professionals living abroad has shifted significantly in the post-pandemic era, as many utilize international relocation as a strategic tool for debt elimination and wealth accumulation. A representative case of this trend is found in the financial profile of Laura and Ethan, a Philadelphia-based couple who relocated to Hanoi, Vietnam, two years ago. Their journey highlights the intersection of global career mobility, aggressive debt management, and the complexities of planning a return to a domestic economy characterized by high interest rates and rising housing costs.

The Philadelphia-to-Hanoi Economic Transition
Laura, 32, and Ethan, 38, began their financial partnership in Philadelphia, Pennsylvania, under the weight of substantial educational debt. Their trajectory is emblematic of a broader millennial struggle with student loans; within the first year of their relationship, the couple collectively eliminated approximately $140,000 in debt. Ethan cleared $80,000 in student loans, while Laura, inspired by the momentum, paid off $60,000 in 11 months.
This aggressive deleveraging served as the foundation for their move to Vietnam. Ethan, an English literature educator, secured a position at an international school—a sector known for providing expatriates with comprehensive compensation packages that often include housing allowances and annual airfare. Laura, previously a software engineer in the non-profit sector, transitioned into full-time graduate studies, pursuing a Master of Public Health (MPH) with a focus on Maternal and Child Health.
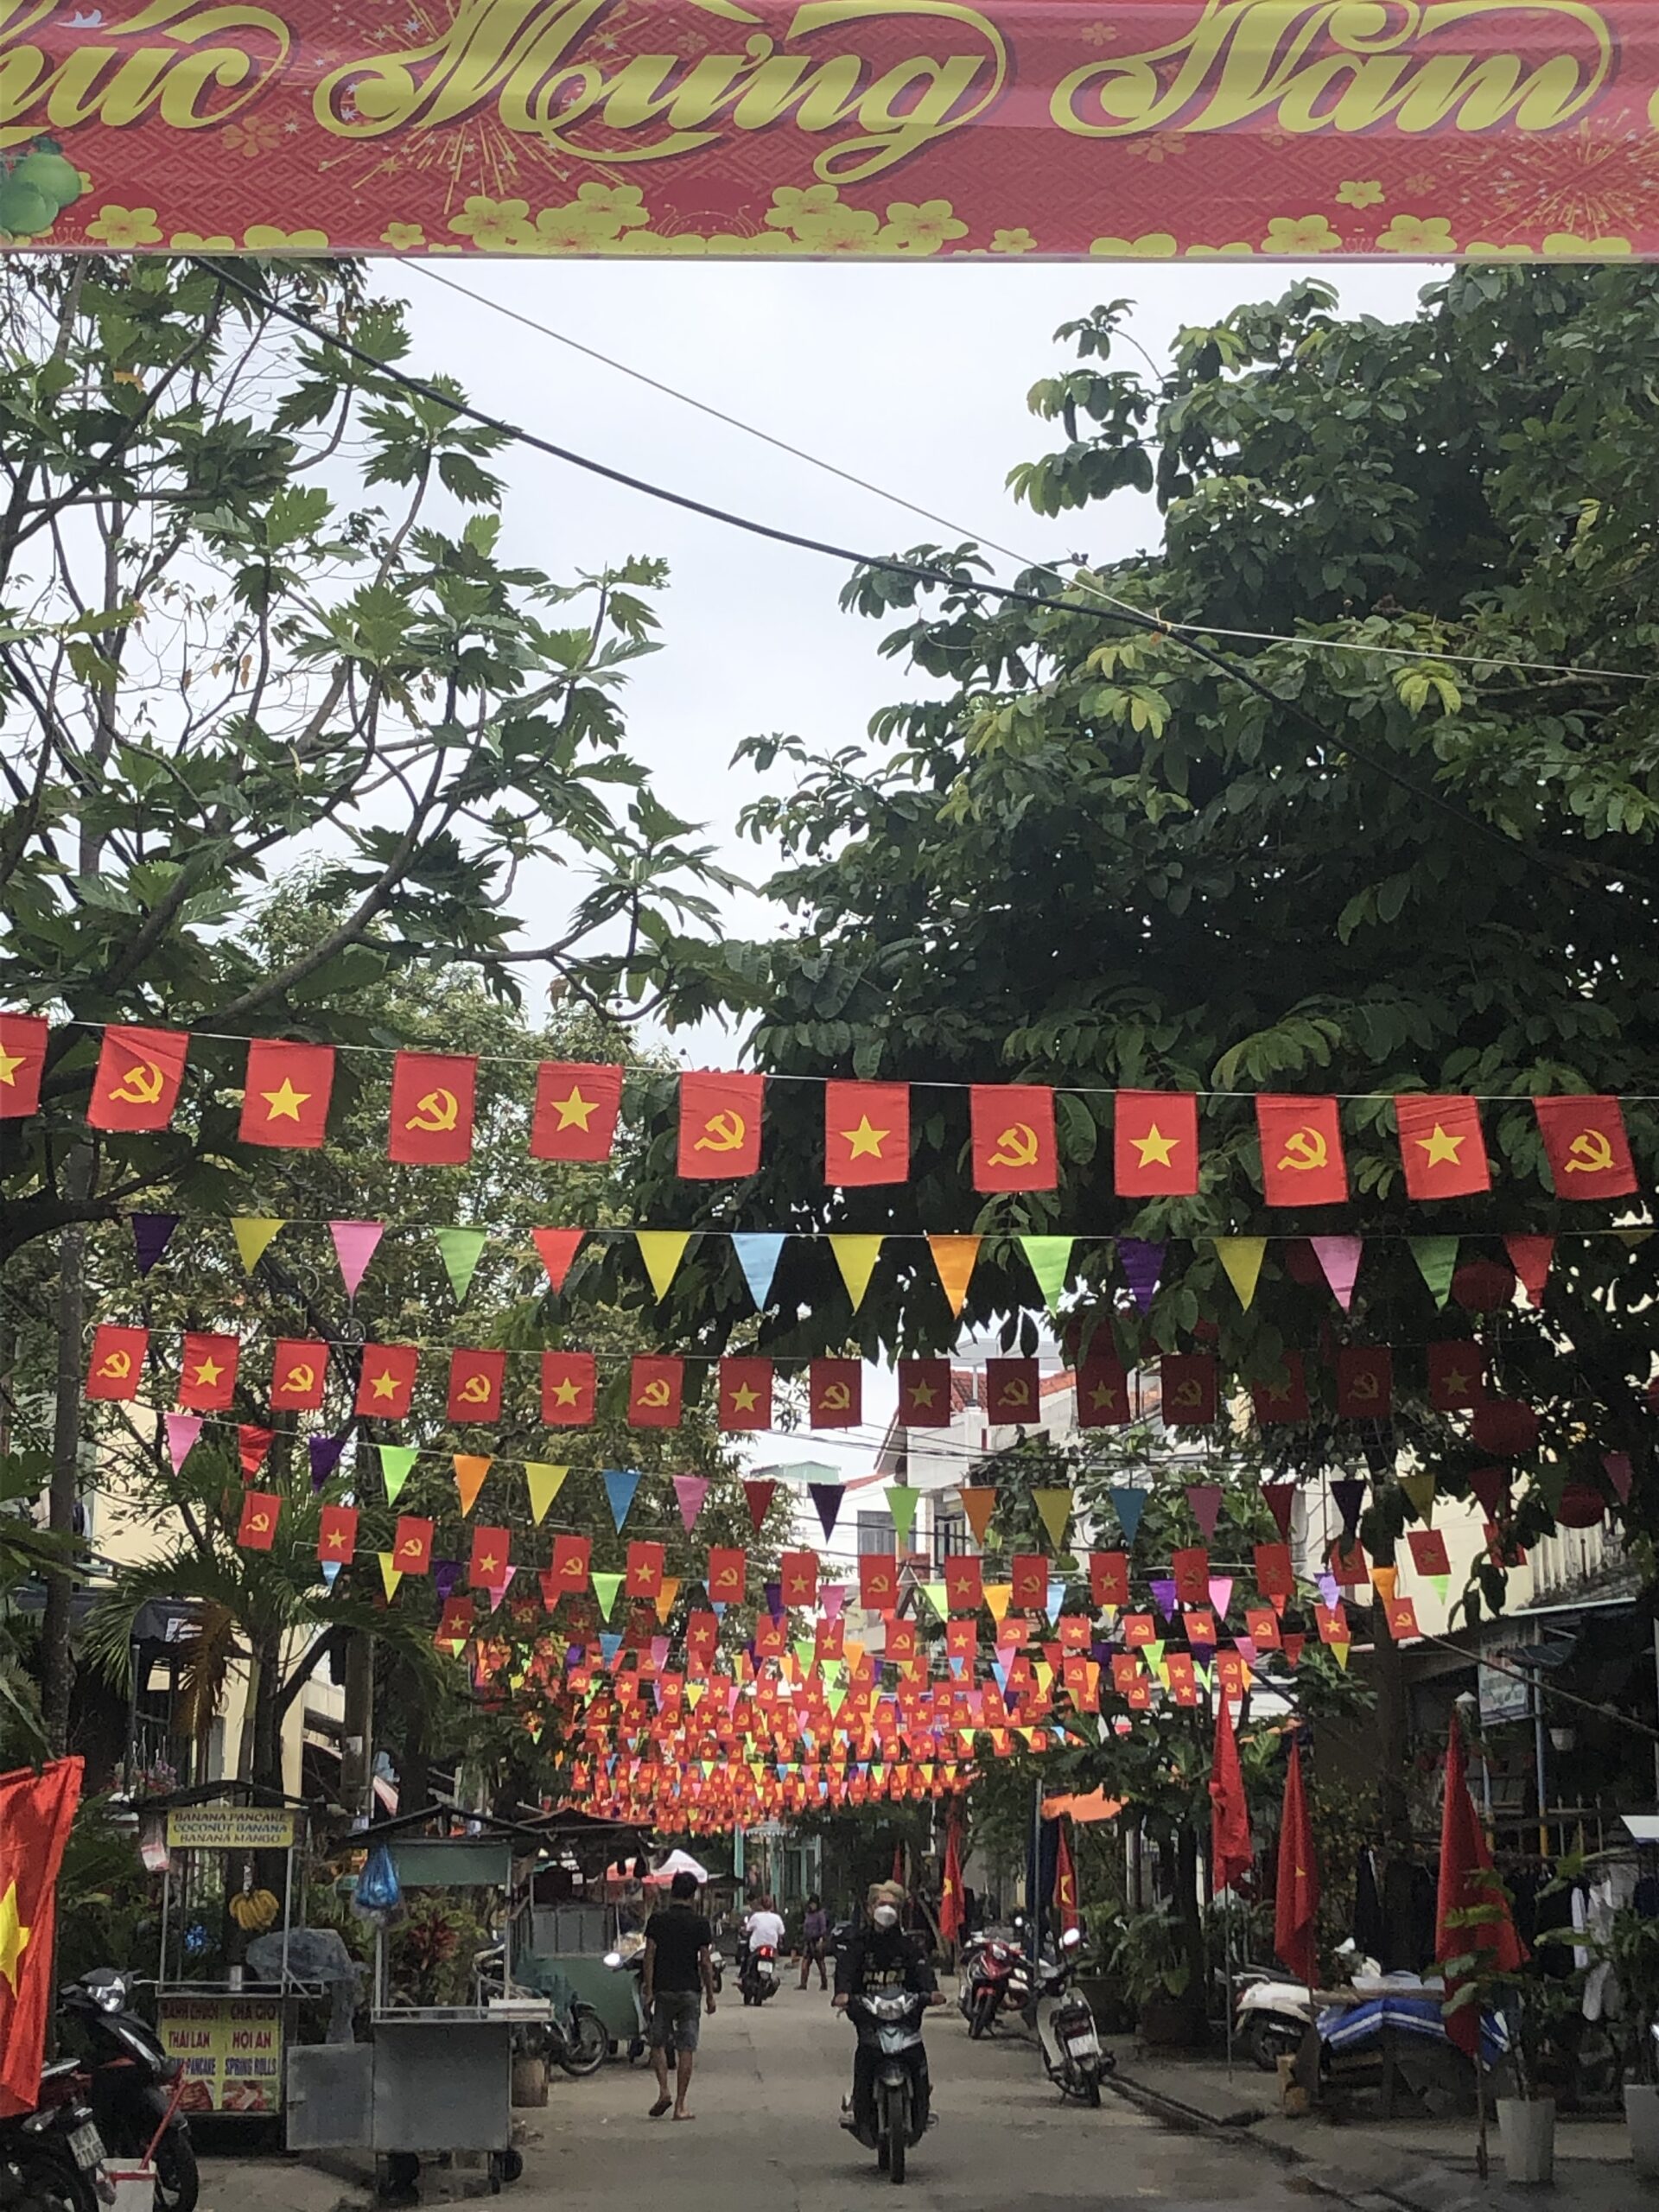
The move to Hanoi represents a classic "geographic arbitrage" strategy. By earning a salary competitive with Western standards while living in a region where the cost of living is approximately 50% to 70% lower than in major U.S. cities, the couple has been able to maintain a high quality of life while simultaneously funding graduate education and building a six-figure cash reserve.
Chronology of Financial Milestones and Career Pivots
The couple’s financial history can be categorized into three distinct phases: the Debt Liquidation Phase, the Career Pivot Phase, and the current Wealth Preservation Phase.

- Debt Liquidation (Pre-2021): During their time in Philadelphia, the couple focused exclusively on solvency. This period was characterized by high-stress employment and a "squirrel-like" approach to savings, where Laura hoarded cash to avoid confronting the reality of her loan balances before eventually pivoting to aggressive repayment.
- Career Pivot and Relocation (2021–2022): The move to Hanoi allowed for significant professional reinvestment. Ethan obtained an accelerated Master’s in Education for a net cost of $4,000, ensuring his long-term certification. Laura exited the tech industry to return to her original passion for public health, enrolling in a $17,000 degree program funded entirely out of pocket to avoid new debt.
- Wealth Preservation (2023–Present): Currently, the couple maintains a net worth of approximately $235,708. However, this wealth is heavily concentrated in cash and low-yield savings, reflecting a conservative "debt-averse" psychology born from their previous financial struggles.
Comprehensive Asset and Expense Analysis
As of mid-2023, the couple’s balance sheet reflects a high degree of liquidity but raises questions regarding long-term inflation protection and market participation.
Asset Distribution
- Cash and High-Yield Savings: $104,370. This includes $76,500 earmarked for a future home down payment and various checking accounts in both USD and Vietnamese Dong (VND).
- Retirement Accounts: $112,555. This is spread across 401k, 403b, and IRA accounts from previous U.S. employers, as well as a Pennsylvania Teacher’s pension (PSERS).
- Taxable Brokerage: $18,783. Held in a diversified set of exchange-traded funds (ETFs) and securities.
The Vietnamese Cost-of-Living Advantage
The couple’s monthly expenditures total $1,741, an exceptionally low figure for a household with a gross annual income of $74,442. Key drivers of this efficiency include:

- Housing: $0 (Employer-provided).
- Dining: $150 (With local meals costing as little as $0.75).
- Transportation: $60 (Motorbike rentals and fuel).
- Healthcare: Minimal out-of-pocket costs, such as $15 dental cleanings.
This surplus allows the couple to save a significant portion of Ethan’s $2,990 monthly net pay, even while Laura is not drawing a traditional salary.
The "Cash-Only" Housing Strategy: A Financial Analysis
A central dilemma facing the couple is their desire to purchase a U.S. home in cash upon their return, a goal driven by a profound fear of debt and current mortgage rates exceeding 7%. Financial analysts, however, often caution against this approach for several reasons.

Opportunity Cost
The primary argument against a 100% cash purchase is the opportunity cost of capital. Historically, the S&P 500 has delivered an average annual return of roughly 7% to 10%. If a mortgage interest rate is lower than the expected market return, an individual is theoretically wealthier by carrying a mortgage and investing the surplus cash in the market. While current mortgage rates are high, the long-term compounding effect of $100,000 invested in equities typically outperforms the interest saved on a primary residence over a 30-year horizon.
Liquidity and Inflation Hedging
Real estate is an illiquid asset. Tying up the vast majority of one’s net worth in a physical structure can leave a household "house rich but cash poor," unable to easily access funds for emergencies or new opportunities. Furthermore, a fixed-rate mortgage acts as a hedge against inflation. As the value of currency decreases over time, the "real" value of the debt diminishes, allowing the homeowner to pay back the loan with "cheaper" future dollars.

Regulatory and Tax Implications for U.S. Expats
For Americans living abroad, retirement planning is complicated by Internal Revenue Service (IRS) regulations, specifically regarding the Foreign Earned Income Exclusion (FEIE).
IRA Contribution Eligibility
To contribute to a Roth or Traditional IRA, a taxpayer must have "earned income." If an expat uses the FEIE to exclude all of their foreign income from U.S. taxation, they may find themselves with $0 in "taxable earned income," rendering them ineligible for IRA contributions. However, if their income exceeds the exclusion limit (approximately $120,000 for 2023) or if they utilize the Foreign Tax Credit (FTC) instead of the FEIE, they may retain eligibility.

Laura and Ethan face a "holding pattern" in their retirement growth. Because Ethan’s income is currently the sole source of support and is likely mostly excluded under FEIE, they have ceased contributions to their U.S. retirement accounts. Analysts suggest that for couples in this position, exploring a Spousal IRA (if eligibility requirements are met) or focusing on taxable brokerage accounts is essential to avoid a multi-year gap in compound interest.
The Psychological Dimension of Expat Re-Entry
Beyond the spreadsheets, the case study highlights the "re-entry anxiety" common among expats. After years of living in an environment where luxury services (like frequent massages and travel) are affordable and basic needs (like housing) are subsidized, the prospect of returning to the U.S. economy can be jarring.

Laura’s reported anxiety stems from three primary factors:
- The Loss of Subsidy: Transitioning from $0 rent to a $2,500+ mortgage or rent payment.
- The "Lurking" Variables: Uncertainty regarding where they will live, the cost of future childcare, and the timing of new employment.
- The Retirement Gap: The psychological weight of seeing retirement accounts stagnate while peers in the U.S. continue their contributions.
Broader Implications and Strategic Recommendations
The case of Laura and Ethan serves as a blueprint for the "Educational Expat" model but also warns of the risks of extreme conservatism. To ensure a stable transition back to the United States, several strategic moves are recommended by financial experts.

Consolidating Retirement Assets
The couple currently manages five separate retirement accounts. Consolidating old 401k and 403b accounts into a single Rollover IRA would allow for better oversight, lower expense ratios, and a more cohesive investment strategy. Moving funds into low-fee total market index funds—such as those offered by Vanguard or Fidelity—can reduce the "drag" of administrative fees which, over decades, can cost investors hundreds of thousands of dollars.
Diversifying the "House Fund"
While keeping a portion of their $104,000 in a High-Yield Savings Account (HYSA) is prudent for a short-term move (1–2 years), the couple may benefit from medium-term vehicles like Certificates of Deposit (CDs) or Treasury bills, which currently offer competitive yields with zero market risk.

The Role of the Pension
Ethan’s PA PSERS pension remains a "wild card." For public employees, understanding the "vesting" period and the impact of the Windfall Elimination Provision (WEP) is crucial. If Ethan does not return to a PA public school, he may be better served by rolling those pension contributions into a private IRA to gain control over the investment allocation.
Conclusion
Laura and Ethan have successfully leveraged international employment to transform their financial identity from debt-burdened to wealth-positive. Their $235,000 net worth at ages 32 and 38 puts them ahead of many of their domestic counterparts. However, their future success depends on transitioning from a "defense-only" posture—characterized by debt avoidance and cash hoarding—to an "offensive" strategy that embraces calculated market risk and the strategic use of leverage. As they prepare for their eventual return to Philadelphia, the couple’s ability to balance their need for psychological safety with the mathematical realities of long-term investing will determine their ability to achieve the American dream of homeownership and family stability.

