
The financial landscape for United States citizens working abroad is characterized by a unique set of opportunities and challenges, particularly when planning for a long-term return to the domestic market. For Laura and Ethan, a Philadelphia-based couple currently residing in Hanoi, Vietnam, the transition represents a critical juncture in personal wealth management. With a combined net worth of approximately $235,700 and zero debt, the couple is currently leveraging geographic arbitrage—the practice of earning a salary in a strong currency or at international rates while living in a region with a significantly lower cost of living. However, as they prepare for a projected return to the United States within the next several years, they face complex decisions regarding retirement catch-up, real estate acquisition strategies, and the mitigation of "re-entry shock" associated with the high cost of American living.

The Expatriate Economic Context: A Two-Year Retrospective
Laura, 32, and Ethan, 38, relocated to Vietnam two years ago to facilitate Ethan’s career as an English literature educator at an international school. This move followed a period of intense financial consolidation in Philadelphia, during which the couple aggressively eliminated substantial student loan debt. Ethan successfully retired $80,000 in debt, while Laura paid off $60,000 within an 11-month window. This history of debt elimination has fostered a significant degree of debt aversion, which now informs their approach to future homeownership.
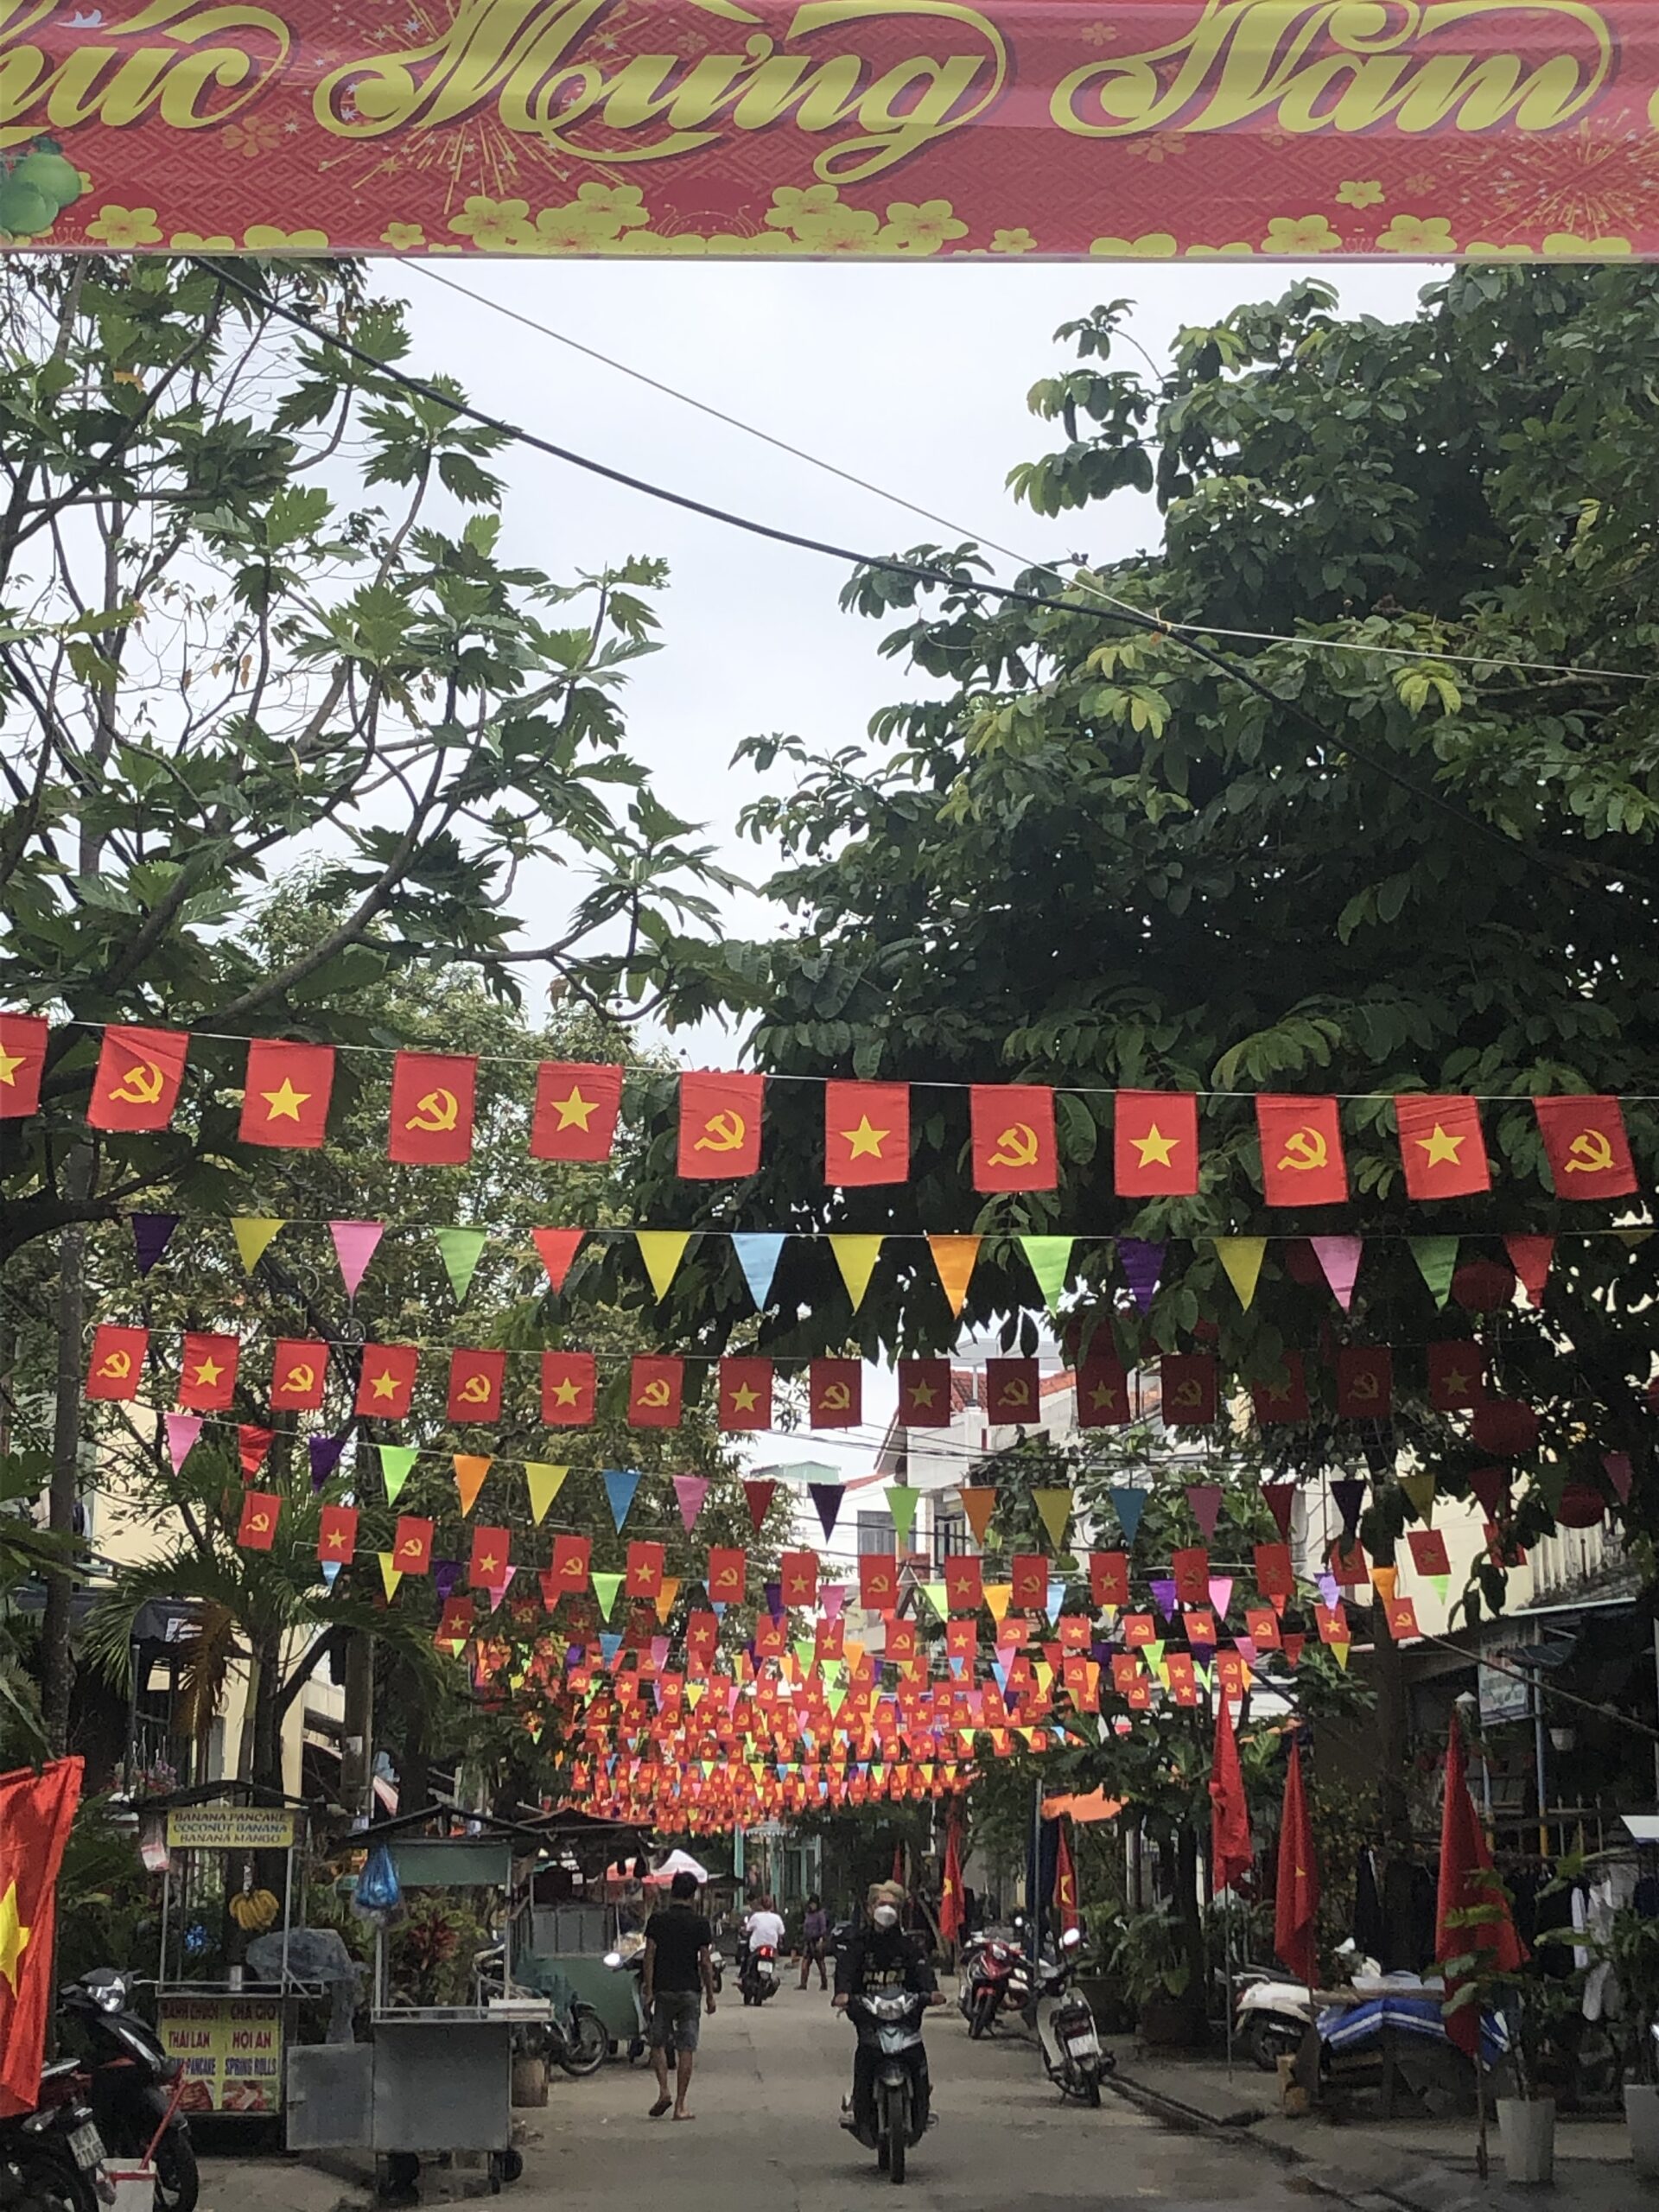
In Hanoi, the couple’s financial structure is bolstered by an expatriate compensation package that includes direct payment of rent by the employer and annual travel reimbursements. This arrangement allows for a high savings rate, even as Laura pursues a Master’s degree in Public Health (MPH) as a full-time student. Their current monthly expenses total approximately $1,741, a figure that covers a lifestyle inclusive of international travel, fitness memberships, and dining, which would cost exponentially more in a major U.S. metropolitan area like Philadelphia.
Chronology of Financial Milestones and Academic Pursuits
The couple’s journey over the last five years serves as a blueprint for aggressive capital accumulation and career pivoting.
- 2018–2020: The Debt Liquidation Phase. Following the commencement of their relationship, the couple prioritized the elimination of $140,000 in combined student debt. This phase required extreme frugality and a singular focus on balance sheet optimization.
- 2021: The Relocation to Southeast Asia. Ethan secured a position at an international school in Hanoi. The transition was intended to provide professional development and an opportunity to build a "house fund" in a low-cost environment.
- 2021–2023: Career Pivot and Continuing Education. Laura transitioned from a role in software engineering back to her original passion for public health. Ethan completed an accelerated Master’s in Education for $4,000 out-of-pocket, ensuring his long-term viability in the education sector.
- 2023–Present: The Accumulation Phase. With debt removed, the couple has focused on liquid savings. They currently hold $76,500 in a high-yield savings account specifically earmarked for a future home down payment.
Comparative Cost of Living and Geographic Arbitrage
The economic advantage of the couple’s current residence is stark when analyzed against U.S. averages. In Hanoi, a meal at a local vegetarian stall costs approximately $2.00, and a bowl of pho is priced at roughly $0.75. Their total grocery and household supply expenditure is $250 per month. In contrast, the United States Bureau of Labor Statistics (BLS) reports that the average American household spends significantly more on food at home and away.

Furthermore, the "invisible" benefits of their expatriate status—such as the employer-covered rent—essentially function as a tax-free subsidy. By eliminating the largest line item in a typical budget (housing), the couple has been able to maintain a liquid cash position of over $100,000 across various checking and savings accounts. However, this high cash-to-asset ratio raises questions regarding opportunity cost and the inflationary erosion of purchasing power.
Strategic Challenges: Retirement and Real Estate
Despite their strong net worth, Laura and Ethan express concern regarding their retirement trajectory. They have not contributed to U.S.-based retirement accounts in nearly two years. This hiatus is partly due to the complexities of the Foreign Earned Income Exclusion (FEIE). For U.S. expats, contributing to a Roth or Traditional IRA requires "earned income" that is not excluded by the FEIE. If a taxpayer excludes 100% of their income using the FEIE and has no other source of U.S. income, their eligible contribution limit is effectively zero.

The couple’s desire to pay for a home in cash upon their return to the U.S. is another point of strategic contention. While a cash purchase eliminates mortgage interest and the psychological burden of debt, financial analysts often point to the "opportunity cost" of such a move.
The Opportunity Cost Analysis
If the couple utilizes $300,000 in cash to purchase a home, they lock that capital into an illiquid asset. If they instead placed that $300,000 into a total market index fund with an average historical return of 7%, and took out a mortgage at 6%, the "spread" or net benefit of investing would be 1%. Furthermore, mortgage interest can often be tax-deductible in the U.S., and inflation effectively devalues the real cost of fixed-rate debt over time. For a couple with 25 to 30 years left until retirement, the compounding effect of $300,000 in the market often outweighs the benefits of a debt-free residence.

Portfolio Review and Fee Optimization
An analysis of the couple’s current assets reveals a fragmented portfolio consisting of old 401(k)s, 403(b)s, a PA teacher’s pension (PSERS), and a taxable brokerage account. A primary recommendation for expatriates in this position is the consolidation of accounts via a Rollover IRA.
The Mechanics of Consolidation
By rolling over dormant 401(k) and 403(b) accounts into a single IRA at a low-cost brokerage (such as Vanguard, Fidelity, or Schwab), the couple gains greater control over their investment selections and fee structures. Laura’s current taxable account at Ellevest holds 13 different securities, including various Vanguard ETFs (VTI, VEA, VWO). While these are high-quality funds, the complexity of 13 holdings may be unnecessary for a portfolio of this size.

The Impact of Expense Ratios
Financial experts emphasize the importance of the "expense ratio"—the annual fee charged by funds. For example, the Vanguard Total Stock Market Index Fund (VTSAX) carries an expense ratio of 0.04%. If the couple’s current accounts are held in actively managed funds with fees of 1% or higher, they could lose tens of thousands of dollars in potential growth over the next two decades.
Implications of Re-entry into the U.S. Market
The transition back to the United States will involve a "triple threat" of financial adjustments:

- Lifestyle Inflation: Moving from $0 rent to a U.S. mortgage or market-rate rent.
- Asset Conversion: Purchasing vehicles and household goods that are currently unnecessary in Hanoi.
- Taxation Changes: Transitioning from the FEIE back to standard U.S. income taxation.
To soften this blow, analysts suggest maintaining a robust emergency fund—which the couple currently possesses—but also beginning to "benchmark" their expectations against the current U.S. housing market. As of 2023-2024, the U.S. market has seen elevated interest rates and low inventory, making the couple’s $76,500 "house fund" a solid down payment, but likely insufficient for an outright cash purchase in a desirable Philadelphia suburb.
Broader Economic Impact and Conclusion
The case of Laura and Ethan reflects a growing demographic of "global nomads" who use international teaching or remote work to front-load their savings. While the short-term gains in Vietnam are substantial, the long-term success of this strategy depends on disciplined re-integration into the U.S. financial system.

By addressing the "devil in the details"—specifically expense ratios, pension service years, and the opportunity cost of cash—the couple can move from a state of anxiety to one of calculated confidence. The transition from a low-cost environment back to a high-cost one is rarely seamless, but with a net worth exceeding $230,000 and a commitment to debt-free living, Laura and Ethan are positioned well above the national average for their age group. Their next steps will require a shift from "hoarding" cash to "deploying" capital in a manner that accounts for inflation and long-term market growth.
As they enter their final year in Hanoi, the focus must remain on clarifying the details of Ethan’s PA pension and determining the most tax-efficient way to resume retirement contributions. Whether they return to the U.S. in 12 months or 36, the foundation they have built in Southeast Asia provides a significant "margin of safety" for their future family and professional goals.

