
The economic landscape for American expatriates has undergone significant shifts in the post-pandemic era, as professionals increasingly leverage global mobility to achieve aggressive financial goals. A prominent example of this trend is found in the case of Laura and Ethan, a Philadelphia-based couple currently residing in Hanoi, Vietnam. Over the past two years, the couple has utilized the significant disparity in cost of living between Southeast Asia and the United States to stabilize their balance sheets, pursue advanced education, and eliminate substantial debt. However, as they prepare for an eventual return to the domestic U.S. market, they face a complex set of financial variables, including high interest rates, retirement savings gaps, and the logistical costs of repatriation.

The Expatriate Economic Advantage and Debt Eradication
The financial journey of Laura and Ethan serves as a blueprint for debt management and strategic relocation. Before their move to Vietnam, the couple prioritized the elimination of approximately $140,000 in student loan debt. Ethan, 38, successfully paid off $80,000, while Laura, 32, eliminated $60,000 within an 11-month period. This aggressive deleveraging provided the foundational liquidity necessary to transition into the international labor market.
In 2021, the couple relocated to Hanoi for Ethan’s role as an English literature teacher at an international school. This move allowed them to access an "expat package" that includes subsidized housing and annual travel stipends. Such arrangements are common in the international education sector, providing a buffer against the inflationary pressures currently affecting the U.S. domestic economy. By removing rent—typically the largest expense for American households—from their balance sheet, the couple has been able to self-fund graduate degrees. Ethan recently completed a Master of Education for a net cost of $4,000, while Laura is currently pursuing a Master of Public Health, estimated to cost $17,000 out of pocket.
A Comparative Chronology of Costs: Hanoi vs. Philadelphia
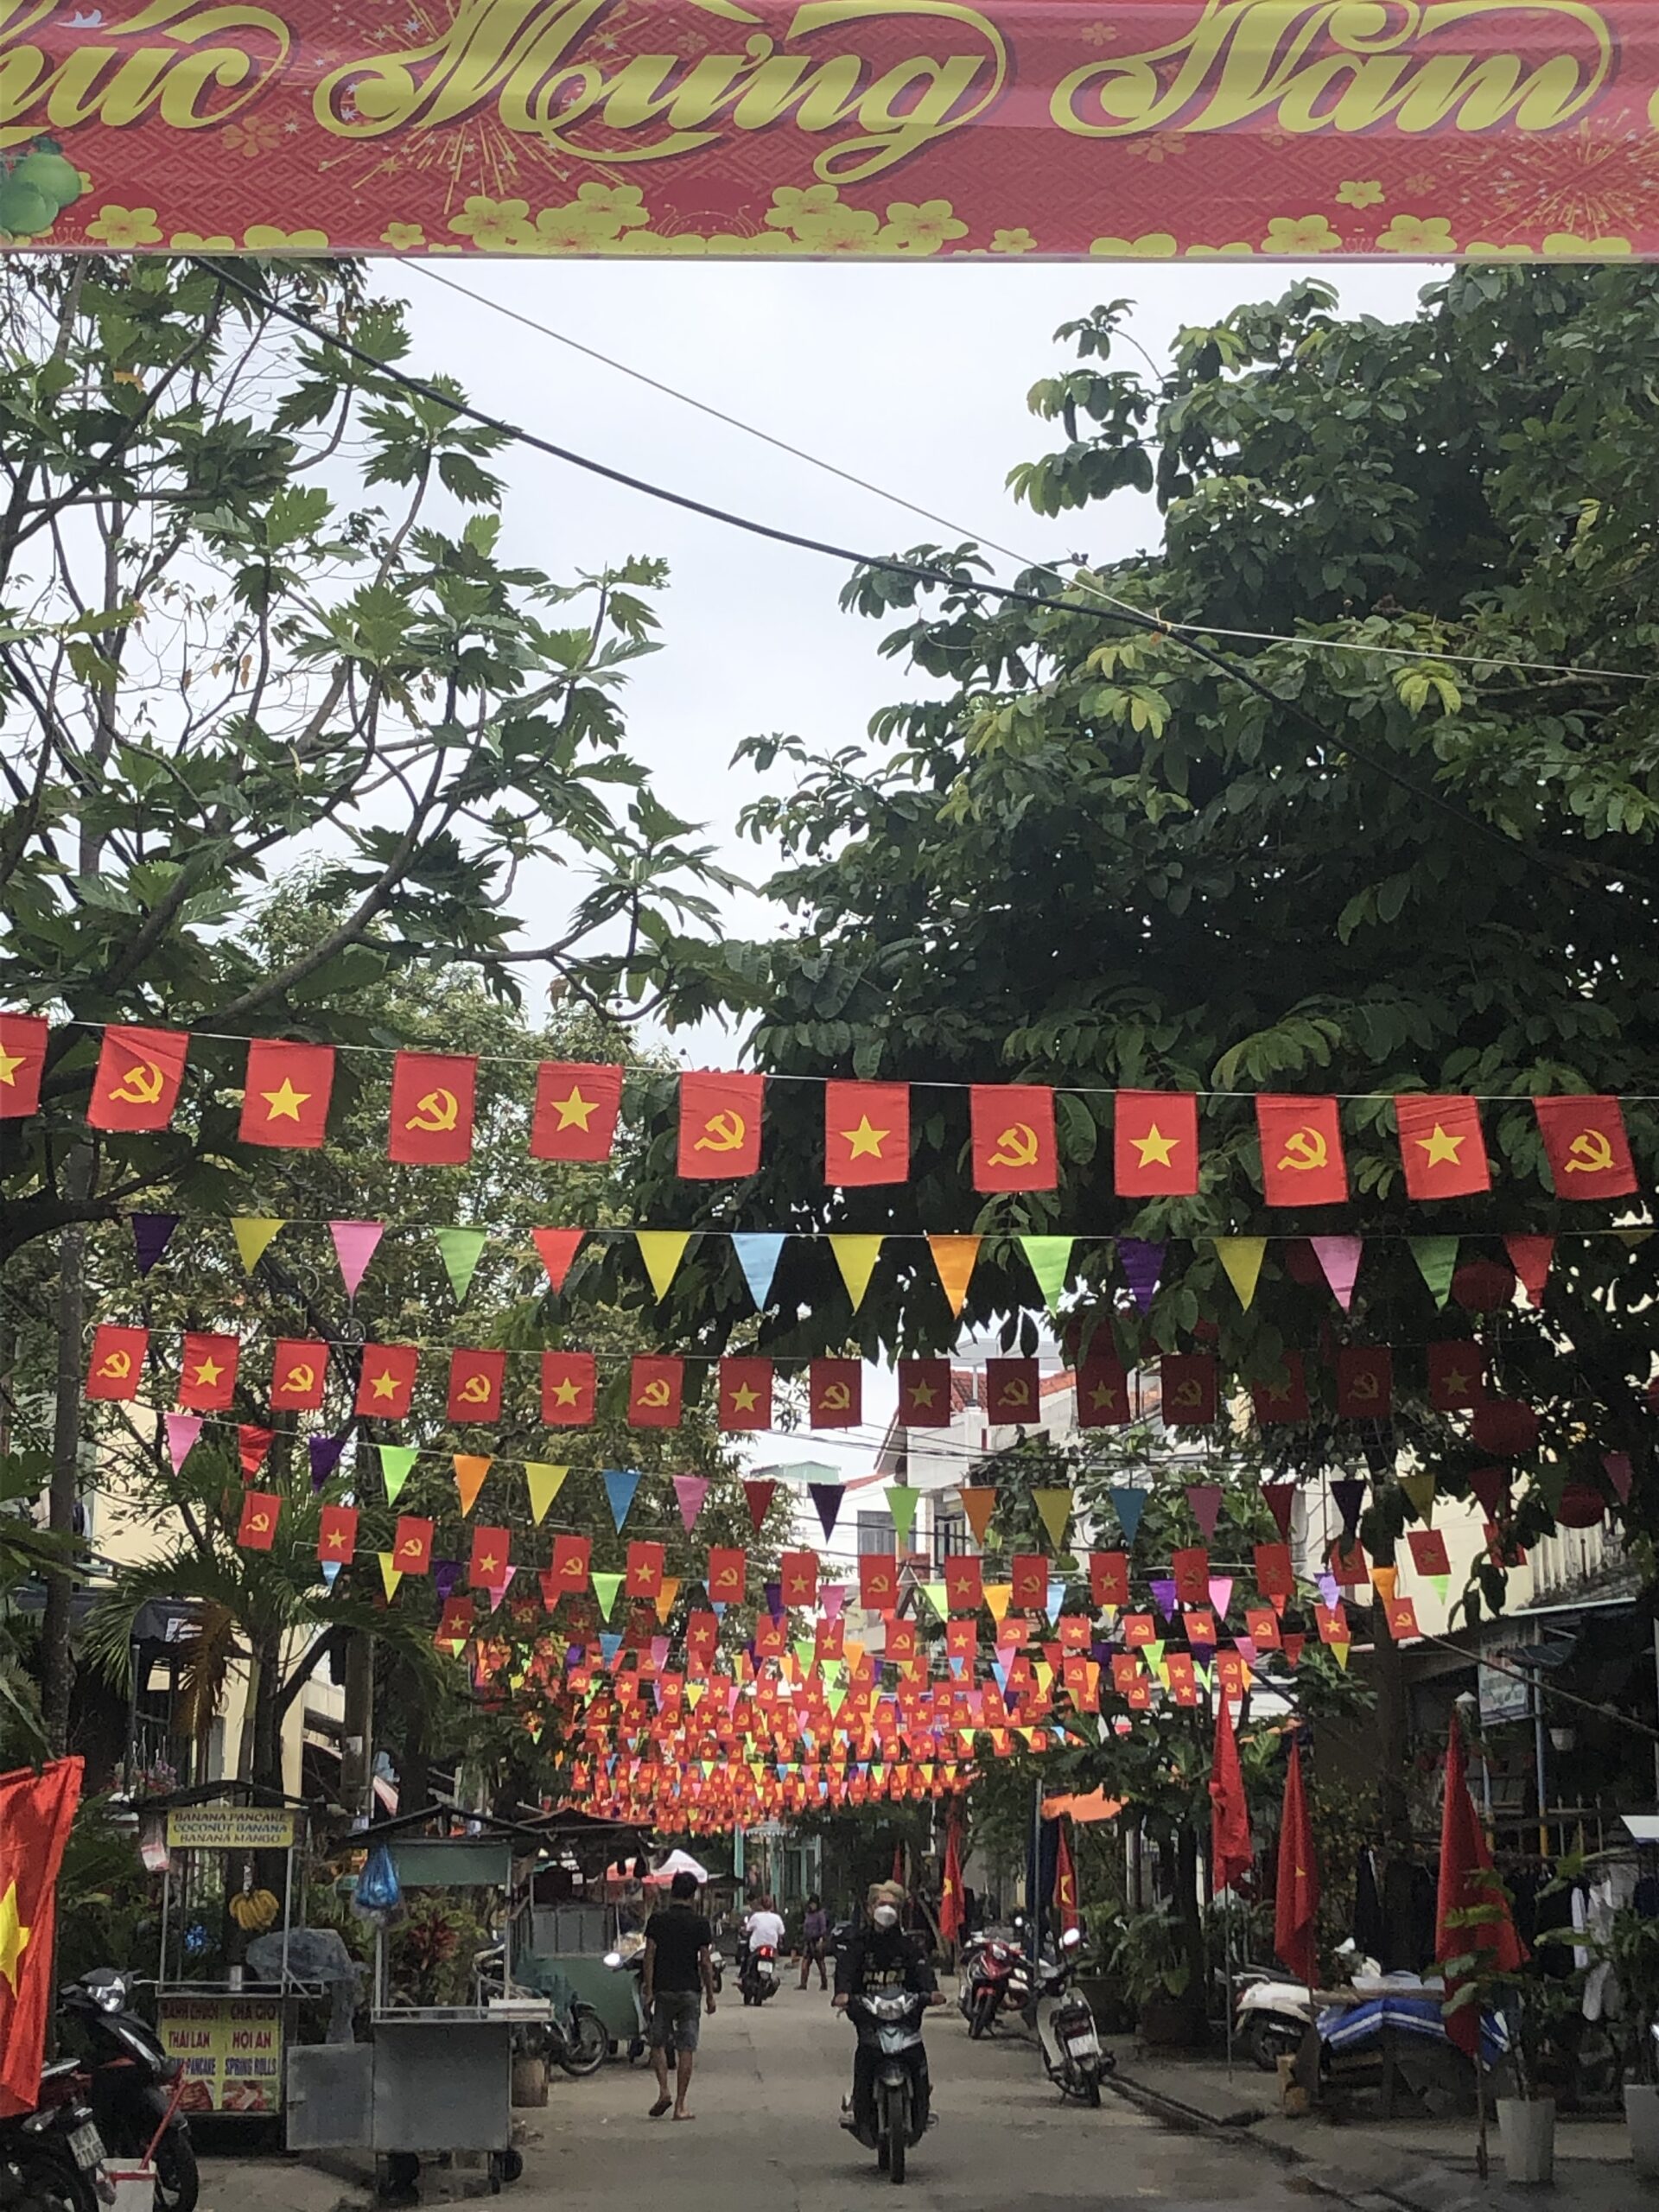
The transition from a high-cost urban center like Philadelphia to a developing economy like Hanoi has created a unique "savings vacuum" for the couple. Data from their current expenditure reports indicates a monthly subtotal of $1,741, covering all living expenses for two adults.
In Hanoi, essential costs are remarkably low:

- Nutrition: A standard local meal, such as pho, costs approximately $0.75, with a vegetarian buffet averaging $2.00.
- Utilities and Services: Monthly electricity averages $50, while unlimited mobile data is secured for $60 per year.
- Healthcare: High-quality dental cleanings are available for $15 out of pocket, a fraction of the cost in the Philadelphia metropolitan area.
In contrast, the couple’s planned return to the United States will involve a "reverse culture shock" regarding purchasing power. According to recent Bureau of Labor Statistics (BLS) data, the Consumer Price Index for all Urban Consumers (CPI-U) has seen significant volatility over the last 24 months. Returning to a market where the median home price in Philadelphia hovers near $250,000 to $300,000, and where childcare and automotive insurance costs are rising, presents a significant hurdle for expatriates who have grown accustomed to the deflationary environment of Vietnam.
The Mortgage Dilemma: Evaluating Cash Purchases in a High-Interest Environment
One of the most pressing questions facing returning expatriates is the strategy for home acquisition. Laura and Ethan have expressed a desire to purchase a home in cash to avoid the debt cycles they previously experienced. They currently hold approximately $76,500 in a high-yield savings account earmarked for this purpose.

However, financial analysts often caution against the "all-cash" approach due to the principle of opportunity cost. While avoiding a 6.5% or 7% mortgage interest rate is psychologically appealing, tying up large sums of liquid capital in a single, illiquid asset can be detrimental to long-term wealth building.
The historical average return of the S&P 500 is approximately 7% to 10% annually. If a couple invests their cash in a diversified brokerage account rather than a house, the compounding interest may outperform the savings gained from avoiding a mortgage. Furthermore, a mortgage serves as a hedge against inflation; as the value of the dollar decreases, the "real" value of the fixed mortgage debt also decreases. Experts suggest that for a returning couple, maintaining a liquidity buffer is essential for navigating the "unknown variables" of a domestic move, such as initial furniture costs, vehicle purchases, and potential gaps in employment.

Navigating Retirement Complexity for Overseas Citizens
For Americans living abroad, retirement contributions are governed by specific IRS regulations, primarily the Foreign Earned Income Exclusion (FEIE). To contribute to a Roth or Traditional IRA, an individual must have "earned income." If an expat excludes all of their foreign earnings from U.S. taxation using the FEIE, they may technically have $0 in "earned income" for the purposes of IRA contributions.
Laura and Ethan have not contributed to their retirement accounts in nearly two years, a common occurrence among expats who prioritize immediate cash savings. Currently, their retirement assets total approximately $112,555, spread across 401ks, 403bs, and IRAs from previous employers.

To rectify this gap, the couple must evaluate their tax filing strategy. By utilizing the Foreign Tax Credit (FTC) instead of the FEIE, or by ensuring they have income that exceeds the exclusion limit, they may regain eligibility for IRA contributions. Additionally, as Laura is currently a full-time student with no income, the couple could explore a "Spousal IRA," which allows a working spouse to contribute to an account for a non-working partner, provided the couple files a joint tax return.
Technical Analysis of Portfolio Management and Expense Ratios
An audit of the couple’s current investment portfolio reveals a need for consolidation and fee optimization. They currently hold multiple accounts with different brokerages (Voya, PenServ, Alerus, Ellevest). For returning expats, the "rollover" process is a critical step in streamlining financial management.

By rolling over old 401k and 403b accounts into a single Traditional or Roth IRA at a low-cost brokerage like Vanguard, Fidelity, or Schwab, investors gain greater control over their asset allocation and, more importantly, their expense ratios.
An expense ratio is the annual fee charged by a fund to cover operating expenses. For example:

- Vanguard Total Stock Market Index Fund (VTSAX): 0.04%
- Typical Managed Fund: 0.50% to 1.00%
Over a 30-year horizon, a 1% fee can reduce a portfolio’s total value by tens of thousands of dollars. Laura’s current brokerage account lists 13 different securities, including various ETFs like VTI and VWO. Simplifying this into a total market index fund can reduce complexity and ensure broad market exposure, which is generally recommended for investors in their 30s who have a high tolerance for market volatility but a low tolerance for unnecessary fees.
Institutional Retirement Systems and the Role of Public Pensions
A significant wildcard in the couple’s financial future is Ethan’s participation in the Pennsylvania Public School Employees’ Retirement System (PSERS). Ethan holds approximately $20,692 in this system. For public employees, pensions represent a guaranteed income stream, but their value is often contingent on years of service.

If Ethan returns to the Pennsylvania public school system, his previous years of service may be "purchasable" or credited toward his vesting period. However, if the couple decides to settle in a different state or if Ethan remains in the private international school sector, the pension may need to be managed differently. Many state pensions offer a "cash-out" option or a "frozen" benefit. For returning educators, consulting with a union representative or a pension specialist is a mandatory step in the repatriation process to ensure institutional benefits are not forfeited.
Long-Term Socio-Economic Implications of the Return Migration
The case of Laura and Ethan highlights a broader demographic trend of "mid-career repatriation." As they look toward the next ten years, their goals—buying a home, starting a family, and securing career-level employment in public health and education—reflect the standard aspirations of the American middle class, albeit viewed through the lens of international experience.

The psychological impact of this transition, often termed "financial anxiety," stems from the loss of the "easy life" in a developing economy. In Hanoi, the couple enjoys the freedom of a single-income household while still saving aggressively. In the United States, they will likely require a dual-income structure to maintain the same rate of savings.
Analysts suggest that the "soft landing" for such couples involves three key pillars:

- The Cash Buffer: Maintaining at least six months of U.S.-based living expenses to cover the transition.
- Employment Continuity: Securing domestic employment contracts before departing the host country.
- Strategic Housing: Renting for the first 6–12 months in the U.S. to allow for market observation before committing to a home purchase.
In conclusion, while the transition from Vietnam to the United States presents significant fiscal challenges, Laura and Ethan’s proactive approach to debt and education has positioned them well above the national average for their age group. By shifting their focus from simple cash hoarding to sophisticated investment management and institutional pension research, they can mitigate the risks of repatriation and leverage their international gains into long-term domestic stability.

